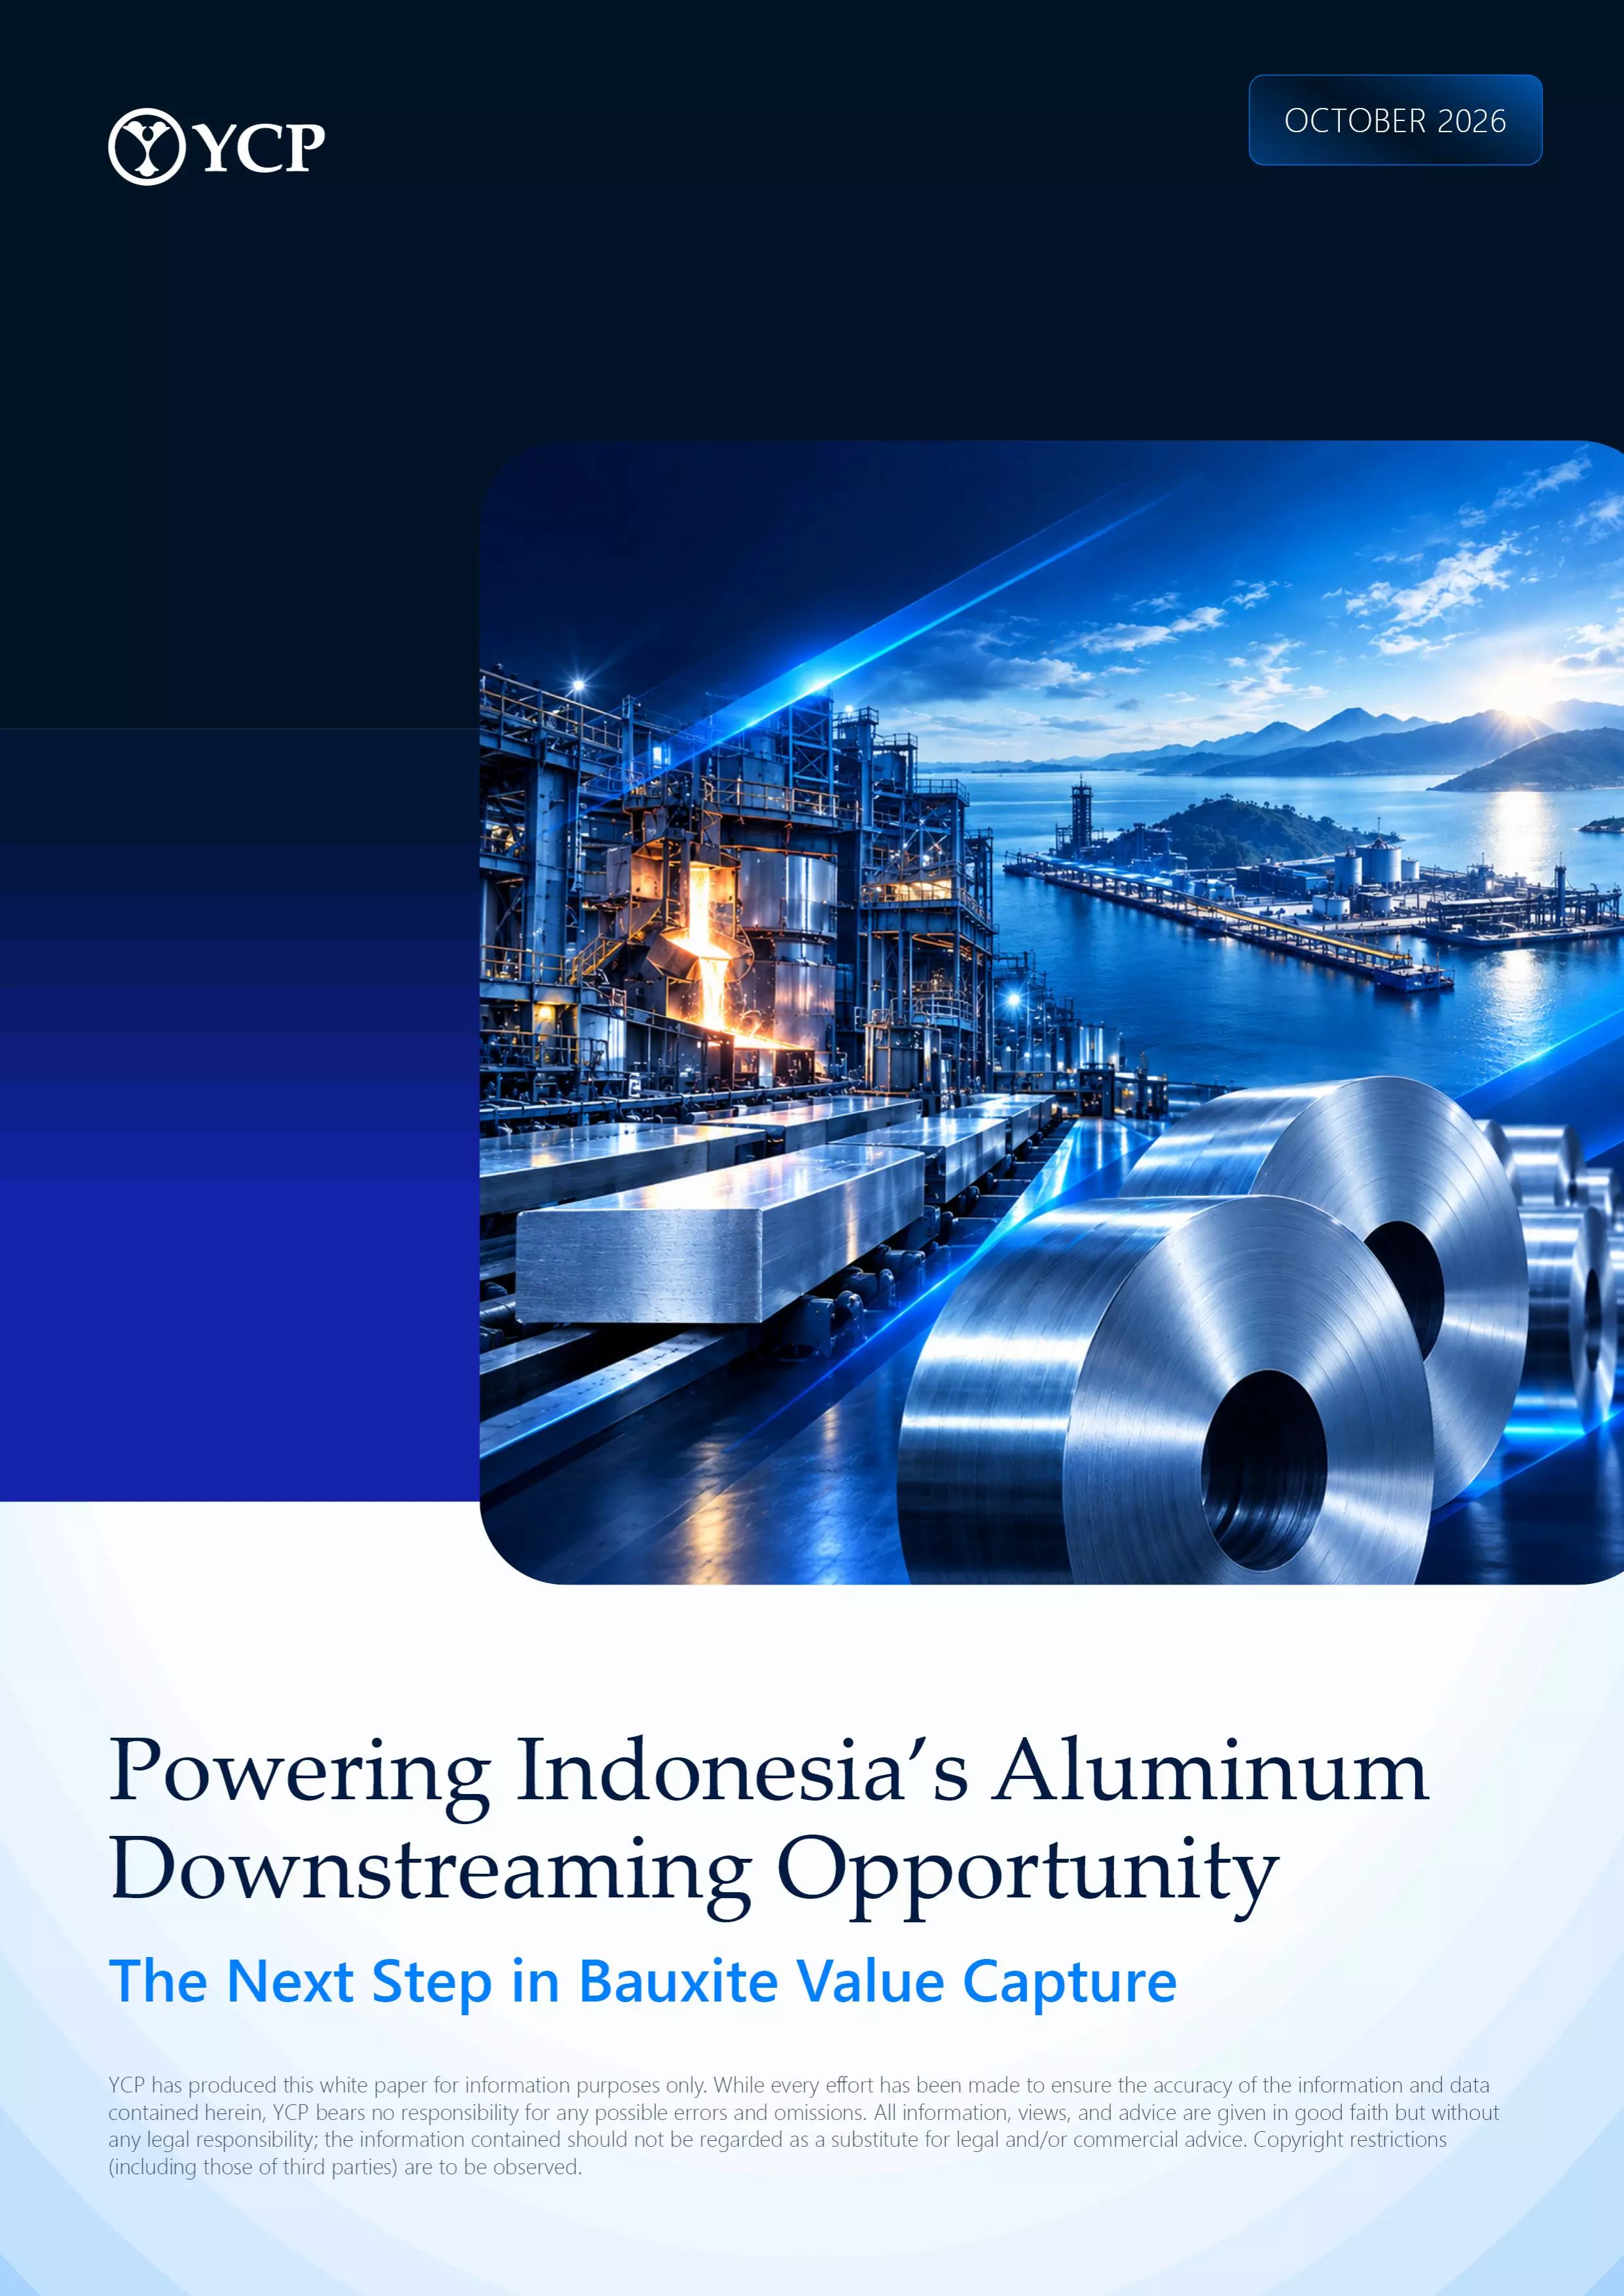
Indonesia’s aluminum industry is moving into the next phase of downstreaming. With roughly 1 billion tonnes of bauxite reserves and alumina capacity expanding rapidly, the remaining value-capture opportunity lies further downstream in primary aluminum smelting and fabrication.
Our latest white paper, “Powering Indonesia’s Aluminum Downstreaming Opportunity: The Next Step in Bauxite Value Capture,” examines where the next stage of value creation could emerge across the aluminum chain, with a focus on smelting economics, policy direction, infrastructure readiness, and the power strategies that will shape long-term competitiveness.
Inside the Report
The value gap: Why the next downstream opportunity lies in primary aluminum smelting and selective fabrication, rather than further alumina expansion alone.
Power economics: How power costs, energy reliability, and project configuration shape the competitiveness of Indonesian aluminum smelters against regional and global producers.
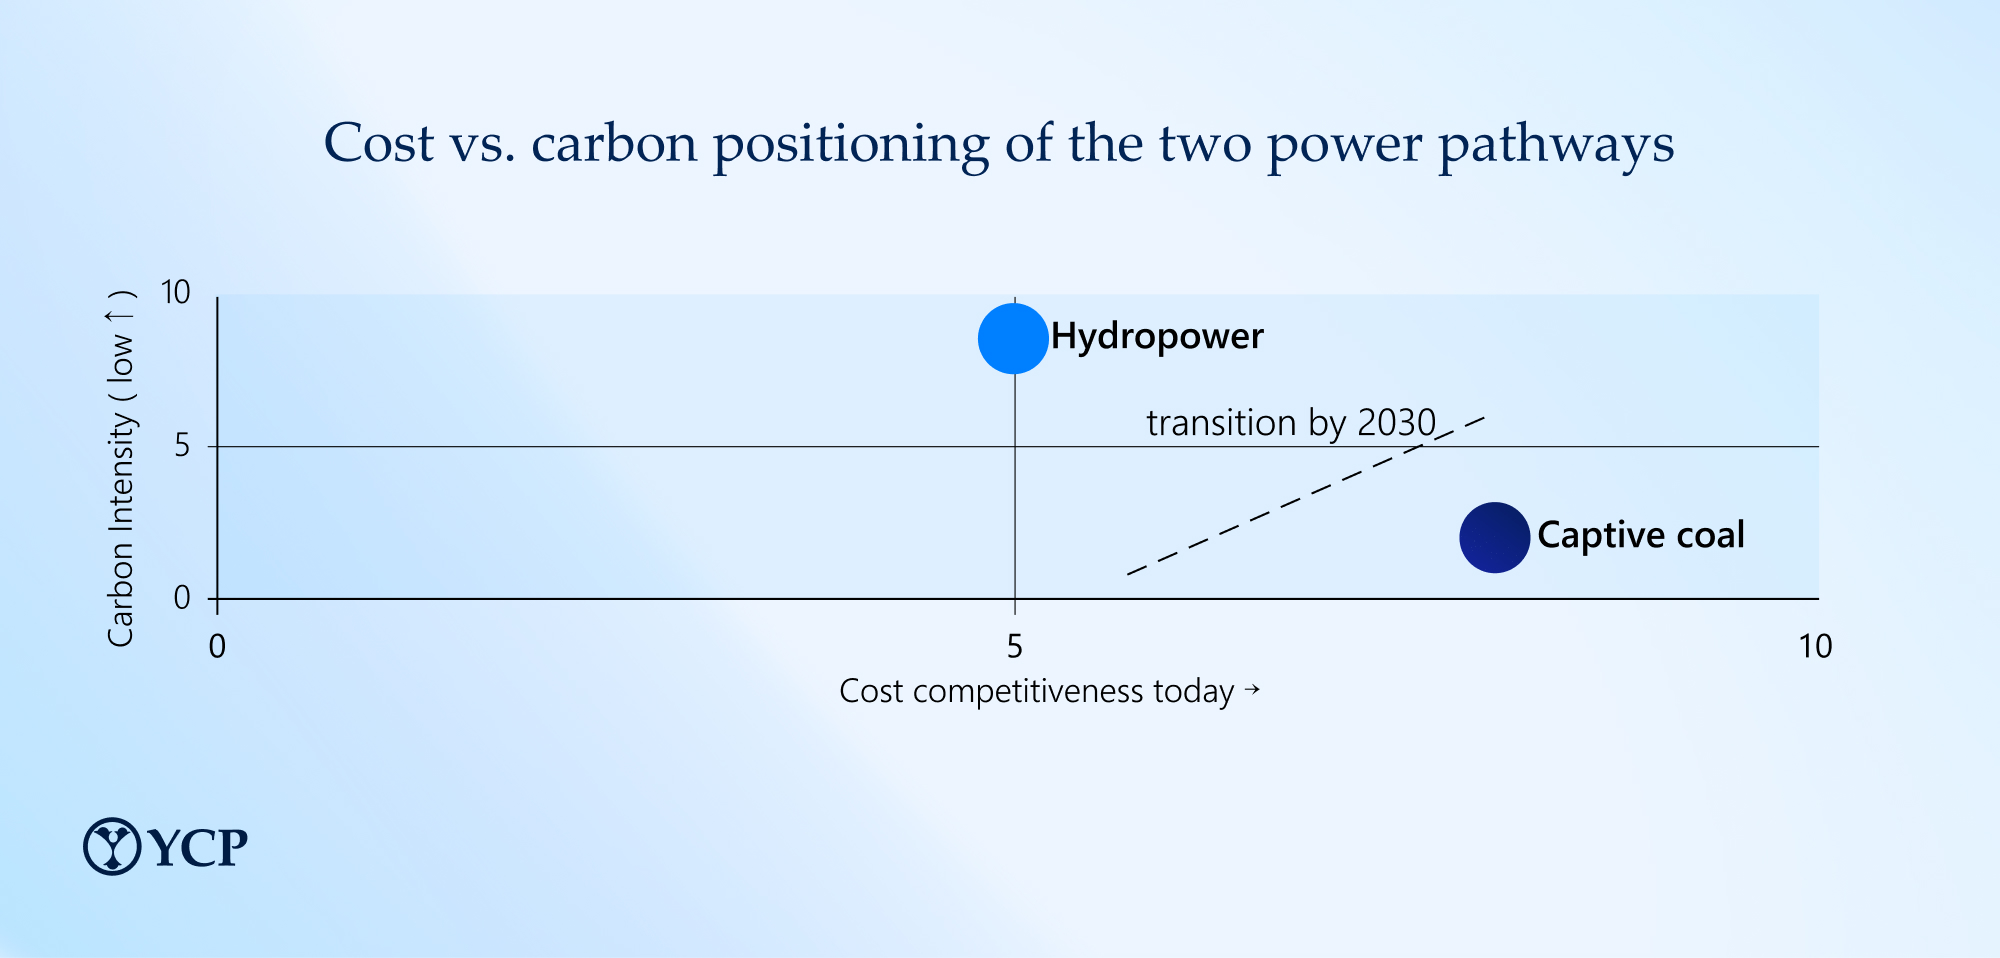
Cost vs. Carbon: What downstreaming policy, infrastructure readiness, CBAM exposure, and lower-carbon power pathways mean for investors and operators.
Indonesia’s aluminum opportunity extends beyond resource availability. Capturing the next stage of downstream value will depend on pairing expanding alumina capacity with competitive, scalable, and progressively lower-carbon power.
Download the full white paper to explore the investment implications, smelting economics, and power strategies shaping the country’s aluminum downstreaming opportunity.
Author
Dhendy Rizki Fadhillah
Dhendy has extensive experience across multiple industries. He specializes in Corporate Strategy, Transformation, System & Operational Excellence, and Change Management.
Recent White Paper
See All